
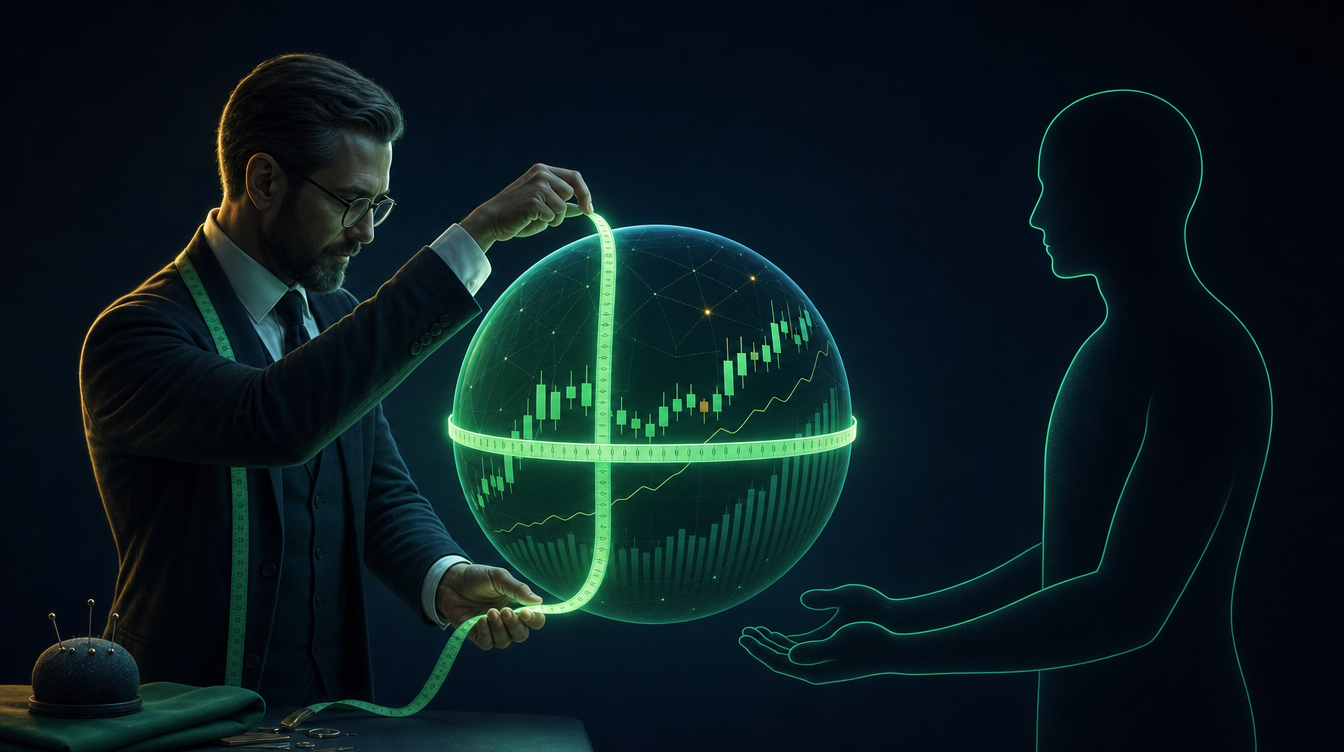



A $200,000 account looks four times better than a $50,000 account, but advertised balance is not the amount you can lose. In a prop firm, the operating resource is distance to drawdown. If the larger account costs much more, adds pressure, and does not improve payouts because of risk constraints, it may be worse than starting small.
The right size is not the maximum fee you can afford. It is the account whose fee is comfortable, whose buffer accommodates the strategy, and whose payout potential remains meaningful without changing behavior. This guide builds that decision around actual risk.
Stop looking at headline balance
A $100K account with 10% static maximum loss starts with a $10,000 buffer. At 6% trailing, it may begin with $6,000 and move upward. That buffer, not $100,000, determines how many losses can be survived.
Call the distance between current equity and breach “usable capital.” Compare sizes using it. A $50K account at 10% static provides $5,000. A $100K account at 5% trailing also starts with $5,000, but its floor may move. The second is not automatically worth twice as much.
Step 1: know historical drawdown
Extract at least six months or one hundred trades. Measure the largest R decline from a peak until recovery. Add room for the future to be worse; multiplying observed drawdown by 1.25 or 1.5 is a prudent reserve, not a guarantee.
If the worst sequence was 8R and you add 50%, the account must survive 12R. A limit accommodating only 8R is badly sized regardless of its headline balance.
Step 2: define risk per trade
Risk should come from the buffer, not nominal balance. One percent of a $100K account is $1,000. If drawdown is $5,000, that single trade risks 20% of usable capital and five theoretical stops end the account.
To tolerate 12R plus reserve, R might be limited to $250-$300. Against nominal balance that looks like 0.25%-0.30%, but against the buffer it is far more coherent. The position-size guide explains how to turn the dollar amount into lots or contracts.
Step 3: translate target into trades
An $8,000 target with $300 risk equals 26.7R gross. At 0.25R expectancy per trade, roughly 107 trades are required on average. If the system produces ten per month, it is not a two-week challenge.
Moving to $200K may double target and proportional risk without reducing R required. The statistical path remains the same; only fee, pressure, and potential payout change. Bigger does not create speed under disciplined sizing.
Step 4: calculate full cost
Include fee, tax, add-ons, reset, and activation. For futures, include likely data and activation charges. Compare how much personal money can be lost across several attempts without affecting essential expenses.
A conservative rule is funding one attempt from a predefined training or trading budget. If failure creates a need to recover the fee in the next challenge, the size is too large.
Step 5: estimate a reasonable payout
Do not multiply balance by an optimistic monthly percentage. Use historical performance adjusted to the rules. Then apply profit split, required buffers, minimum withdrawals, and profitable-day conditions.
A smaller account traded calmly can produce more than a large one where fear suppresses setups or consistency is breached. Economically useful size is the one sustained across several payout cycles.
When to choose a small account
- It is your first evaluation with the firm.
- The exact drawdown has not been simulated.
- A large fee would change your behavior.
- You want to test execution and payouts.
- The strategy still has a limited sample.
A small account is a pilot. It reveals how the firm calculates the day, what slippage appears, and how support responds. Potential payout is lower, but information reduces errors before scaling.
When a large account makes sense
- You have already withdrawn from that firm or equivalent conditions.
- The fee is a small part of the budget.
- The strategy has hundreds of measured trades.
- Risk per position remains conservative.
- Maximum allocation supports growth without redundant accounts.
Large size should amplify a stable process rather than compensate for low expectancy. If excessive risk is required to make payouts “worth it,” expectations and account do not fit.
A large account does not remove daily loss
Daily drawdown can be much tighter than maximum loss. If a system opens correlated positions or scales entries, calculate simultaneous loss. Three trades at 0.5% nominal add to 1.5% before slippage; with a 3% daily boundary, two sequences approach danger.
Set an internal stop below the official one, perhaps half. The gap absorbs execution errors and prevents one session from deciding the challenge.
Trailing drawdown changes size selection
Usable capital evolves under trailing. An account can begin with $6,000 and lose room after floating profit. If the floor locks at starting balance, the early stage deserves lower risk. If it never locks, the process must live with that restriction permanently.
Read the comparison of trailing-drawdown firms and never treat sizes with different mechanisms as equivalent.
Several small accounts or one large one
Multiple accounts can diversify operational risk but multiply fees, rules, and mistakes. Some firms allow merging while others cap allocation. Trade copying may be restricted.
One large account is administratively simple. Several small accounts reduce dependence on a single credential only when they can be managed legally and without correlated overexposure. Never assume copying is allowed.
Forex and futures express size differently
Forex marketing emphasizes nominal balance. In futures, dollar drawdown, maximum contracts, and scaling matter more. A futures “50K” account with $2,000 trailing should be compared through that $2,000 and contract limits, not against a forex 50K label.
Before changing markets, review the guide to futures prop firms. The same displayed size can represent very different capacity.
A practical example
A trader has 7R historical drawdown and wants 12R of room. A 50K account offers $5,000 static. At $300 risk, it holds 16.7R, enough for reserve. Its $4,000 target equals 13.3R.
The 100K version costs almost twice as much, provides $6,000 trailing, and has an $8,000 target. At $300 it holds 20R but needs 26.7R to pass, while the floor moves. The larger account contains more dollars but a worse target-to-buffer relationship for this process. Choosing 50K is rational.
Create three personal limits
- Per-trade risk: a fixed amount or stable formula.
- Internal daily loss: lower than the firm's limit.
- Weekly loss: a mandatory pause and review point.
These boundaries turn account size into an operating framework. Without them, a larger account merely increases the amount available for improvisation.
Common mistakes
- Treating advertised balance as personal money.
- Risking a nominal percentage without checking drawdown.
- Buying the maximum through fear of “starting too small.”
- Ignoring expected retry cost.
- Projecting payouts from unproven returns.
- Failing to distinguish forex from futures.
Frequently asked questions
Does a larger account always pay more? Only when returns can be maintained and withdrawn under the rules. Balance creates no profit by itself.
Should everyone start with the minimum? Not always, but it is a sensible pilot when the firm is unfamiliar. The smaller buffer must still cover historical drawdown.
Can extra risk compensate for small size? That removes the benefit. If larger R is needed to make payout feel worthwhile, adjust expectations or wait for scaling.
Does profit split matter? Yes, after risk compatibility. A 100% split on an account you cannot preserve is worth less than 80% on one that fits.
When should size increase? After an error-free sample and preferably a payout. Scale evidence rather than excitement.
A three-scenario stress test
Before buying, model normal, bad, and severe months. Normal uses average expectancy. Bad uses historical maximum drawdown. Severe adds 50% to that drawdown and higher cost. The account should survive bad conditions comfortably and severe conditions without immediate breach.
Then apply one operational error: duplicate order, delayed stop, or correlated loss. This is not permission to be careless; it acknowledges that real execution is imperfect. If one small mistake destroys the account, usable room is too narrow.
Size and personal cash flow
The fee should not compete with rent, debt, or emergency savings. Keep prop-firm spending in a separate budget and assume no payout. This removes urgency from every trade.
Set a yearly cap as well as a per-attempt cap. A “small” account repurchased repeatedly can cost more than one carefully chosen larger account. Review cumulative fees quarterly.
What size does not solve
More balance does not fix negative expectancy, inconsistent execution, or ignorance of rules. It amplifies dollar outcomes. A trader who violates daily loss on 25K will likely do the same on 200K because the behavioral pattern scales.
Use demo until process is stable. Buy size only after capital is the constraint rather than skill, discipline, or understanding.
A written decision record
Before checkout, write the selected size and rejected alternatives with one sentence for each reason. Include usable capital, R tolerated, target in R, and total fee. This creates a baseline for later review. After the first month, compare actual figures with the record rather than judging from emotion. If the account fails, the document shows whether the original assumptions were wrong or execution departed from them. If it succeeds, it prevents increasing size merely because the recent outcome feels easy. Keep the record with screenshots of the rules because product terms can change. A sizing decision is strongest when another person could read the sheet and reproduce the same conclusion from the same inputs.
Revisit the calculation whenever fee, drawdown, payout rule, or strategy statistics change. Size is not a permanent identity. It is a decision based on current evidence, and moving down can be as rational as moving up when conditions tighten.
When uncertain, choose room over appearance and evidence over ambition. Preserve optionality for the next decision.
Conclusion
Build a minimal calculator
A simple sheet needs eight inputs: nominal balance, maximum loss, daily loss, drawdown type, target, fee, per-trade risk, and historical R drawdown. Calculate usable capital after reserve, R tolerated, R needed for target, and fee per $1,000 of buffer.
The last metric reveals expensive sizes. If an account costs $500 and provides $5,000 room, it costs $100 per $1,000 usable. Another costing $300 with $4,500 room costs $66.67. The first may still win through payout or other rules, but risk pricing is visible.
Simulate a withdrawal before selecting
Project a conservative first payout and subtract the buffer that must remain. Under trailing, check whether the floor locks or recalculates. A large account requiring most early profit to stay inside may take longer to produce cash than expected.
Also model three months without payout. If fee or frustration would cause risk changes, reduce size. The correct account survives a period without reward.
Allocation and scaling
Maximum allocation can make a large starting account unnecessary. Scaling increases balance after several cycles. Although slower, it ties growth to results. Buying the maximum immediately pays today for capacity that may not yet be used.
Compare total ceiling and merging. If a small account can grow, duplicate fees may be avoided. If it cannot and the strategy is already validated, a larger starting size may be justified.
The psychology of the number
Some traders calculate risk correctly but react to P&L. Losing $400 on 200K may feel small as a percentage despite being a complete R. A $2,000 gain can create euphoria. Hide balance or display results in R.
Appropriate size keeps figures emotionally neutral. If potential profit draws attention before the stop, the account is too large for the current stage.
Review after the first month
Compare live trades with the test: frequency, slippage, drawdown, and mistakes. Do not scale because balance is positive. Require a sample and preferably one complete payout cycle.
If planned risk felt routine and execution stayed consistent, consider the next size. If entries were reduced through fear, remain or move down. Actual behavior outweighs any preliminary calculation.
Purchase checklist
- The buffer covers historical drawdown plus reserve.
- The target in R fits actual frequency.
- The fee belongs to a budget considered lost upfront.
- Post-payout behavior is understood.
- Daily loss fits correlated positions.
- Risk need not change to make profit feel worthwhile.
The correct size comes from four numbers: historical drawdown in R, usable capital, risk per trade, and personal cost. The headline balance is secondary. Start with an account that tolerates an ordinary sequence without the fee changing decisions.
After validating the process and receiving payouts, consider scaling plans or greater allocation. Use the firm directory to compare actual boundaries. A properly sized account should feel manageable, not impressive.
Published on
The community
Join us on our mission to become the most influential family in funded trading.
Join the DiscordDon't miss anything
Promotions, news and funded trading analysis straight to your inbox.
No spam. Unsubscribe anytime.